Small-Cap Spotlight Report: NCC (LSE: NCC)
Many great companies still can’t resist ‘diworsifiying’ in the quest for growth. Maynard Paton studies IT specialist NCC and its costly folly beyond software escrow.
Many great companies still can’t resist ‘diworsifiying’ in the quest for growth. Maynard Paton studies IT specialist NCC and its costly folly beyond software escrow.
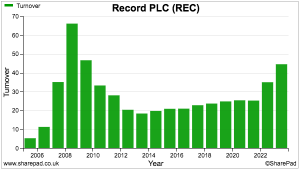
Screening for consistently high margins and ROE leads to currency manager Record. Maynard Paton weighs up the small-cap’s super cash flow, well-paid workforce, diversification ambitions
Devoted company bosses do not always create great returns for outside shareholders. Maynard Paton studies chocolate retailer Hotel Chocolat and the board’s decisions and composition.
Screening for consistently high margins and ROE leads to property franchisor Belvoir. Maynard Paton weighs up the small-cap’s acquisitive history, super cash flow, visible management
Newspaper publisher Reach trades on a P/E of 3. Maynard Paton believes the rock-bottom rating reflects a pension scheme ‘black hole’. Let me start by
Screening for a growing dividend, lowly valuation, net cash and decent director ownership leads to 40-bagger James Latham. Maynard Paton studies the timber distributor’s history,
WANdisco has owned up to ‘significant accounting irregularities’ and the prospects for shareholders now look grim. Maynard Paton revisits the software developer to identify the
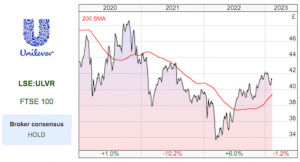
IPO activity on AIM has hit a 20-year low, which Maynard speculates could be a buy signal for shares on the junior market. Plus coverage
Higher energy bills are supporting significant dividend advances at Telecom Plus. Maynard Paton weighs up the group’s illustrious growth and ambitious targets against a leadership
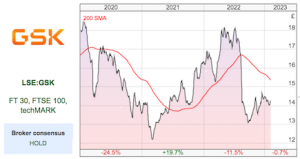
As the FTSE 100 reaches a new peak, Maynard looks at another blue-chip measure setting record highs. Plus coverage of GSK, DARK, SOM and TPX.
Quartix’s vehicle-tracking services have delivered consistently attractive financial ratios. Maynard Paton spotlights how new customers and a good-value workforce are counterbalancing pricing pressures and rising
Strix is the world’s leading developer of kettle safety controls, but a recent profit warning has sent the shares tumbling. Maynard Paton wonders whether the