Weekly Commentary 07/06/21: Expectations Gap
Last week Brent crude was up +4% to $71 per barrel which helped BP +6% and Shell +4% lead the FTSE 100. Since the 7th
Last week Brent crude was up +4% to $71 per barrel which helped BP +6% and Shell +4% lead the FTSE 100. Since the 7th
The FTSE 100 is up +10% since the start of the year, currently at 7,120. The best performing stock in the FTSE 100 in H1
The FTSE was quiet remaining just above 7,000 through the week. Looking at the five best performing stocks since the start of the year (Ashstead
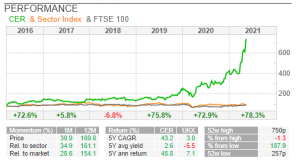
This week I look at Cerillion, the telco billing Group; Sanderson Design Group, the wallpaper and interior design company (previously known as Walker Greenbank); SigmaRoc, which is acquiring concrete quarries, and Games Workshop which needs no introduction to most readers.
Markets sold off last week, with the FTSE 100 down -2.3%, S&P 500 -2.8% and Nasdaq 100 -4.5%. The best performing index was Brazil’s Bovespa,
It’s good to have management with experience of boom and bust cycles, so Bruce looks at two companies run by Chairmen over 80 years old. With the FA Cup and Champions League Final later this month he starts with some football stories from his time at Seymour Pierce.
Bruce looks at tech stocks reporting Q1 results in the US, Google vs Facebook, and the resurgence of Microsoft. Plus a mix of UK companies reporting this week, including Tristel, Water Intelligence, HeiQ and Sylvania.
Markets have been very strong recently, so it’s important not to get carried away. Bruce looks at stocks with accrued income, % revenue recognition, acquisition and fair value accounting adjustments.
Bruce wonders if value vs momentum factors is really the best way to think about companies on the stock market. He also looks at the Novacyt profit warning, The Mission, and two high performance stocks: Volex and Impax.
We are most of the way through result season for companies with December year ends. Bruce discusses how companies with patchy track records can border on evasive in their RNS disclosure, without quite crossing the line to unacceptable. Often the share price reactions suggests that investors aren’t fooled though.
There have been at least 15 ten baggers since the March low in the UK. Bruce looks at 4 stocks that now have a fair wind behind them, that should be geared into further recovery.
Bruce compares a couple of Direct Carrier Billing (DCB), mobile payment platforms: Boku v Bango. He wonders if platform economics has become too popular, with the benefits well recognised but not downside. Also Ocean Wilsons, the Brazilian (Salvador, Bahia) port business.